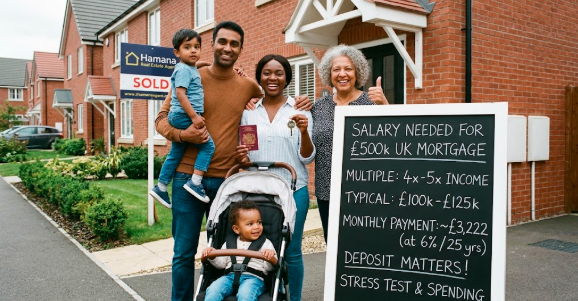
What salary needed for 500k mortgage in the UK? Most lenders cap borrowing at around 4 to 5 times your annual income, so you typically need £100,000 to £125,000 (single or joint). At 4.5 times income, it’s about £111,111. Some lenders go to 5.5 or 6 times for higher earners and certain professions, which brings the figure down to roughly £83,000 to £91,000. At today’s rates near 6%, the repayment is about £3,222 a month over 25 years.
Those multiples are a starting point. UK lenders also check what you spend and owe, so your final figure can be higher or lower.
Want your own monthly figure? Use the mortgage calculator and enter £500,000 with your rate and term. The calculator labels amounts in dollars, but the repayment maths is identical for pounds. Set the property tax, insurance and HOA fields to zero.
A £500k Mortgage Is Not a £500k Home
Your mortgage is the loan. Your property price is the loan plus your deposit. The salary you need depends on the loan, so a bigger deposit lowers it.
| Deposit (LTV) | Property price for a £500k loan | Deposit needed |
|---|---|---|
| 5% (95% LTV) | ~£526,316 | ~£26,316 |
| 10% (90% LTV) | ~£555,556 | ~£55,556 |
| 20% (80% LTV) | £625,000 | £125,000 |
A higher deposit usually earns a lower rate too. Many lenders price 95% LTV deals higher and check them more closely.
Salary Needed for a £500k Mortgage by Income Multiple
| Income multiple | Salary needed |
|---|---|
| 4x | £125,000 |
| 4.5x | £111,111 |
| 5x | £100,000 |
| 5.5x | £90,909 |
| 6x | £83,333 |
Each lender sets its own multiple, and it varies with your income, deposit, job and profession. There is also a market-wide limit: the Bank of England’s Financial Policy Committee caps lending at 4.5 times income or more to 15% of new residential mortgages. That is why mainstream approvals cluster around 4 to 4.5 times, and the higher multiples tend to go to higher earners and some professions.
Joint Applications: Two Salaries Count
| Household income | Multiple of £500k | How achievable |
|---|---|---|
| £125,000 | 4.0x | Widely available |
| £120,000 (2 × £60,000) | 4.17x | Widely available |
| £111,000 | 4.5x | Mainstream limit |
| £100,000 (2 × £50,000) | 5.0x | Some lenders, with low debts |
| £90,000 | 5.6x | Fewer lenders |
| £85,000 | 5.9x | Specialist or profession-based |
| £80,000 | 6.25x | Rarely available |
Joint applicants combine incomes, but both people’s debts and credit histories count.
What Your £500k Mortgage Costs Each Month
Repayment mortgage, fixed for the whole term, excluding fees. The Moneyfacts average 2-year fixed rate was 5.97% and the 5-year fixed 6.01% on 22 October 2026, with the lowest widely available deals around 4.9% at lower loan-to-value.
| Rate | 25 years | 30 years | 35 years |
|---|---|---|---|
| 4.5% | £2,779 | £2,533 | £2,366 |
| 5% | £2,923 | £2,684 | £2,523 |
| 6% | £3,222 | £2,998 | £2,851 |
| 7% | £3,534 | £3,327 | £3,194 |
One percentage point matters: moving from 5% to 6% over 25 years adds about £299 a month. Over the full term, a 25-year loan costs about £376,885 in interest at 5% and about £466,452 at 6%.
Does Your Salary Cover the Payment?
Here is the 25-year payment as a share of gross income:
| Gross income | At 5% (£2,923) | At 6% (£3,222) |
|---|---|---|
| £100,000 | 35.1% | 38.7% |
| £111,111 | 31.6% | 34.8% |
| £125,000 | 28.1% | 30.9% |
Those shares come out of take-home pay, which is lower than gross after Income Tax and National Insurance. At £100,000, the payment can feel heavy once you add council tax, energy and travel.
See your split: open the payment breakdown and the amortization schedule. For the formula behind these numbers, read how to calculate your monthly mortgage payment.
How UK Lenders Assess Affordability
Under FCA rules, lenders must check you can afford the loan rather than rely on a multiple alone. In practice they look at:
- Income after tax and National Insurance, not just gross salary.
- Committed spending: loans, car finance, credit cards, student loan repayments, childcare and maintenance.
- Essential spending: food, utilities, council tax, transport and insurance, taken from your declaration or the lender’s model, whichever is higher.
- A stress test. Lenders must allow for rates rising, with a rise of at least one percentage point where the deal isn’t fixed for five years. Each lender sets its own stress rate, so a loan priced at 6% might be tested at 7% or higher. At 7%, a 25-year loan costs £3,534 a month.
- Credit history. Missed payments, defaults and CCJs in the past six years can limit your options.
Bonuses, overtime and commission can count if you can show they are regular. Lenders typically review a couple of months of bank statements.
Buying Costs: Stamp Duty
Stamp Duty Land Tax (England and Northern Ireland) is paid on top of the deposit. For a standard buyer:
| Price band | Rate |
|---|---|
| Up to £125,000 | 0% |
| £125,001 to £250,000 | 2% |
| £250,001 to £925,000 | 5% |
On a £625,000 home (£125,000 deposit, £500,000 loan), stamp duty is £21,250. On a £550,000 home it is £17,500. First-time buyer relief applies only to homes up to £500,000, so it doesn’t help at these prices. If you already own a property, a 5% surcharge applies on every band. Scotland and Wales have their own taxes, and rates change, so check GOV.UK before you budget.
How to Borrow £500k on a Lower Salary
- Save a bigger deposit. It lowers the loan you need and often the rate.
- Pay down debts and cancel unused credit. Each monthly commitment cuts what lenders will offer.
- Add a joint applicant, knowing their debts count too.
- Choose a longer term. Moving from 25 to 35 years at 6% lowers the payment from £3,222 to £2,851, but costs more interest overall.
- Use a whole-of-market broker, who can match you to lenders with higher multiples for your profession.
- Overpay when you can. At 6% over 25 years, an extra £200 a month would clear the loan in about 22 years and save roughly £66,500 in interest. Many lenders limit penalty-free overpayments, so check your terms.
For a smaller loan, see what a £60,000 mortgage costs per month. If you’re in your 40s or 50s, read can a 46-year-old get a 25-year mortgage.
Ready to test your numbers? Open the mortgage calculator, then take your best-case and worst-case figures to a regulated mortgage broker.
Frequently Asked Questions
What salary do I need for a £500k mortgage in the UK?
Typically £100,000 to £125,000 (4 to 5 times income). At 4.5 times it’s about £111,111, and some lenders going to 5.5 or 6 times could lend to incomes of around £83,000 to £91,000.
Can I get a £500k mortgage on £80,000?
It’s 6.25 times your income, which few lenders will offer. A large deposit, no debts or a profession some lenders favour could help, but most approvals sit nearer 4.5 times.
Can I get a £500k mortgage on £100,000?
That’s 5 times income, which some lenders offer if your debts are low and your credit is clean. It isn’t guaranteed.
Is £90,000 enough for a £500k mortgage?
It’s about 5.6 times income, so you’d need a lender that goes above 5 times. It’s possible, but fewer lenders will say yes.
How much deposit do I need for a £500k mortgage?
The deposit depends on the property price, not the loan. For a £625,000 home, 20% down is £125,000 and leaves a £500,000 mortgage.
How much is a £500k mortgage a month?
About £3,222 at 6% over 25 years, £2,998 over 30 years, or £2,684 at 5% over 30 years. These exclude fees.
Can two people combine salaries?
Yes. Two earners on £60,000 each have £120,000, or 4.17 times £500,000. Both people’s debts and credit histories count.
Can I get a £500k mortgage if I’m self-employed?
Yes, but lenders usually want proof of income over a couple of years, so prepare your accounts or tax calculations in advance.
Does a bigger deposit lower the salary I need?
Yes, because it shrinks the loan. A £625,000 home with £125,000 down needs a £500k loan; with £225,000 down you’d need only £400k, or £88,889 at 4.5 times.