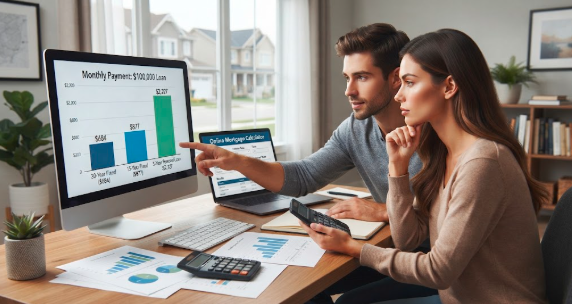
A $100000 loan per month. On a 30-year fixed mortgage at 7.28%, a $100,000 loan costs about $684 a month in principal and interest. On a 15-year mortgage at 6.60%, it’s about $877 a month. A 5-year personal loan at 14% runs about $2,327 a month.
The number swings a lot because three things drive it: your interest rate, your loan term, and the type of loan. Below you’ll find payment charts for each, what a real monthly housing payment looks like once taxes and insurance are added, and how to lower what you pay.
Rates referenced here come from Freddie Mac’s weekly survey (October 1, 2026): 7.28% for a 30-year fixed and 6.60% for a 15-year fixed. Your rate will differ based on credit, down payment and lender.
Want your own number right now? Run your exact rate and term in our mortgage calculator.
Monthly Payment on a $100,000 Mortgage (Principal and Interest)
This table shows principal and interest only. It does not include property taxes, insurance or PMI.
| Interest Rate | 15-Year | 20-Year | 30-Year |
|---|---|---|---|
| 5.00% | $790.79 | $659.96 | $536.82 |
| 6.00% | $843.86 | $716.43 | $599.55 |
| 6.50% | $871.11 | $745.57 | $632.07 |
| 7.00% | $898.83 | $775.30 | $665.30 |
| 7.28% | $914.55 | $792.19 | $684.21 |
| 8.00% | $955.65 | $836.44 | $733.76 |
Two patterns stand out:
- Rate matters: Moving from 6% to 7% on a 30-year loan adds about $66 a month for every $100,000 borrowed.
- Term matters more: Cutting a 30-year loan to 15 years raises the payment by roughly $240 at 6% but saves a large amount of interest (more on that below).
The Formula Behind the Payment
Lenders use the standard amortization formula:
M = P × r(1 + r)ⁿ ÷ [(1 + r)ⁿ − 1]
- M = monthly principal and interest payment
- P = loan amount ($100,000)
- r = monthly interest rate (annual rate ÷ 12)
- n = number of monthly payments (years × 12)
Quick shortcut: At 7.28% over 30 years, every $1,000 you borrow costs about $6.84 a month. Multiply by 100 for a $100,000 loan and you get roughly $684.
You can see the full math, year by year, in the amortization schedule on our calculator.
Your Real Monthly Cost: Add Taxes, Insurance and PMI
The principal-and-interest figure is only part of what you pay each month. Mortgage lenders often collect property taxes and homeowners insurance through escrow, which is the “T” and “I” in PITI.
Here’s an illustration using assumptions (your costs will differ by state, home and insurer):
| Monthly Cost | Example Amount |
|---|---|
| Principal and interest (30-year, 7.28%) | $684 |
| Property taxes (assumed $1,375 per year) | $115 |
| Homeowners insurance (assumed $1,500 per year) | $125 |
| Estimated total | about $924 |
If your down payment is under 20% on a conventional loan, you may also owe private mortgage insurance (PMI). HOA dues, if any, are paid separately but still count toward what you can afford.
So when someone asks what a $100,000 mortgage costs per month, the honest range is roughly $700 to $1,000 or more once the extras are included. Our calculator lets you add your own tax, insurance, PMI and HOA numbers to see the full payment.
Total Interest: What a $100,000 Loan Really Costs
A lower monthly payment usually means more interest over time.
| Loan | Monthly Payment | Total Interest | Total Repaid |
|---|---|---|---|
| 30-year at 7.28% | $684.21 | $146,316 | $246,316 |
| 15-year at 6.60% | $876.61 | $57,791 | $157,791 |
The 15-year loan costs about $192 more per month but saves roughly $88,500 in interest. Whether that trade-off works depends on your budget and your other financial goals. A shorter term is not automatically better if it stretches your cash flow too thin.
Monthly Payment on a $100,000 Personal Loan
If your $100,000 loan is a personal loan rather than a mortgage, the payments are much higher because the terms are shorter and the rates are higher.
| Rate (APR) | 3-Year | 5-Year | 7-Year |
|---|---|---|---|
| 10% | $3,227 | $2,125 | $1,660 |
| 14% | $3,418 | $2,327 | $1,874 |
| 18% | $3,615 | $2,539 | $2,102 |
At 14% over five years, you’d repay about $139,600 in total, which is roughly $39,600 in interest. Personal loan rates vary widely by credit profile, so compare offers before committing.
How Much Income Do You Need for a $100,000 Mortgage?
A common budgeting guide is the 28/36 rule: housing costs around 28% of gross monthly income, and total debt payments around 36%. Lenders set their own limits, so treat this as a starting point.
- A $684 principal-and-interest payment lines up with about $29,300 in annual gross income at 28%.
- The full $924 estimated payment lines up with about $39,600 a year.
If you’re building toward a purchase, these guides may help:
- How much home can I really afford?
- Can I get a mortgage for $60K?
- What’s the best down payment amount for a house?
5 Ways to Lower Your Monthly Payment
- Make a bigger down payment. A smaller loan means a smaller payment, and 20% down avoids PMI on conventional loans.
- Compare multiple lenders. Even a quarter-point difference changes the payment and total interest. Our guide on which bank is easy for a home loan explains how to shop smart.
- Improve your credit before you apply. Lenders price loans by risk tier, so a stronger profile can mean a lower rate.
- Choose the right loan type. First-time buyers have options worth comparing. See the best home loan for first-time buyers.
- Extend the term, carefully. A longer term lowers the monthly payment but raises total interest.
Can You Pay It Off Faster?
Yes, and the savings are bigger than most people expect. On a $100,000 30-year loan at 7.28%, adding $100 a month toward principal pays the loan off in about 20.5 years instead of 30 and saves roughly $53,700 in interest. Use the extra-payment field in the mortgage calculator to test your own amount. Check your loan terms first to confirm extra payments go to principal and carry no prepayment penalty.
Frequently Asked Questions
How much is the monthly payment on a $100,000 loan?
For a 30-year mortgage at 7.28%, about $684 in principal and interest. For a 15-year mortgage at 6.60%, about $877. A 5-year personal loan at 14% is about $2,327.
How much is a $100,000 mortgage per month for 30 years?
Between roughly $537 (at 5%) and $734 (at 8%) in principal and interest, before taxes and insurance.
How much is a $100,000 loan per month for 15 years?
Between about $791 (at 5%) and $956 (at 8%), principal and interest only.
What is the monthly payment on a $100,000 loan at 6%?
$599.55 on a 30-year term and $843.86 on a 15-year term.
How much interest will I pay on a $100,000 mortgage?
At 7.28% over 30 years, about $146,316. At 6.60% over 15 years, about $57,791.
What salary do I need for a $100,000 mortgage?
Using the 28% guideline, about $29,300 a year for principal and interest alone, or around $39,600 with estimated taxes and insurance. Lenders also weigh your debts, credit and down payment.
Is the payment the same for every $100,000 loan?
No. Rate, term, loan type, taxes, insurance and PMI all change it. A mortgage and a personal loan of the same size have very different payments.
How do I calculate the payment myself?
Use the amortization formula above, or enter your numbers into our free mortgage calculator.
Work Out Your Exact Payment
Your rate, term and local costs make your number different from any chart. Open the calculator, enter your loan details, and see your payment, total interest and full amortization schedule in seconds. Browse more guides on the MortgageCalculatorTool blog.